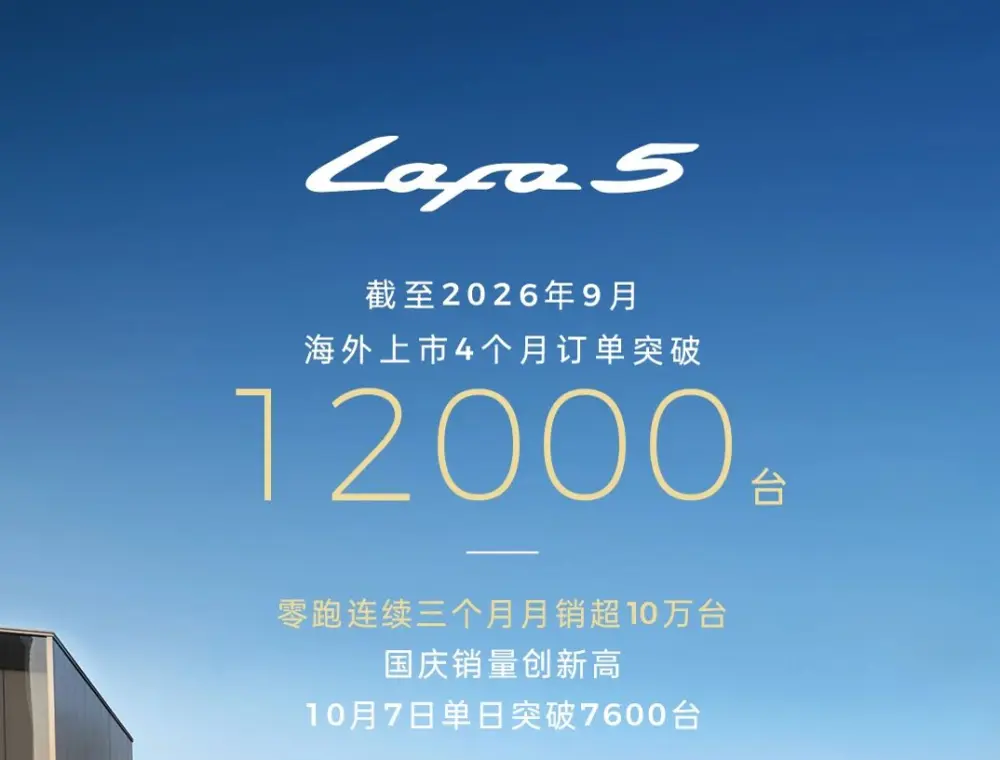
Leapmotor Lafa5's 12,000 Overseas Orders: The Signal vs. the Noise
Leapmotor's B01 sedan—badged as the Lafa5 in overseas markets—has accumulated more than 12,000 orders in its first four months of export availability, according to company statements released on October 13. On the surface, this is another data point in the relentless drumbeat of Chinese EV expansion: a once-obscure startup racking up order volume abroad. But the number deserves forensic scrutiny. Twelve thousand orders is neither trivial nor transformative. Context matters: annual global EV sales exceed 14 million units; 12,000 orders over four months implies a run-rate of roughly 36,000 units annually across all export markets. For Leapmotor, that is meaningful traction. For the global industry, it is a rounding error—unless it signals something larger about the viability of the "China export playbook" outside price-sensitive emerging markets.
To understand why the B01 matters beyond its own sales tally, we need to rewind. Leapmotor (零跑汽车) was founded in 2015 in Hangzhou, backed by Zhejiang Dahua Technology—a surveillance equipment giant—and has always positioned itself as a value-focused, vertically integrated EV maker. Its early models (S01 coupe, T03 city car) were largely domestic plays. The turning point came in 2023–2024, when Leapmotor pivoted hard toward exports and, crucially, inked a strategic partnership with Stellantis. That deal gave Leapmotor access to Stellantis's global distribution network—a critical advantage for a startup lacking its own overseas dealership footprint. The B01, a mid-size electric sedan aimed at the heart of the family car market, is Leapmotor's first truly global product, and the Lafa5 nameplate is its export passport.
This report dissects the B01's engineering, supply chain economics, competitive positioning, and the uncomfortable realities that corporate press releases tend to gloss over. We interrogate whether Leapmotor's export surge is built on sustainable economics or the same debt-fueled volume game that has crushed margins across China's domestic market. And we assess what the Lafa5's order book actually tells us about the next phase of the China EV export wave.
Engineering the B01: A Value Play with Hidden Constraints
Let's start with the hardware. The Leapmotor B01 is a five-seat electric sedan measuring approximately 4,770 mm in length, 1,880 mm in width, and 1,490 mm in height, with a wheelbase of 2,730 mm. That places it squarely in the mid-size sedan segment—a hotly contested battleground in China (think BYD Qin Plus, Aion S) and a market where Western consumers typically expect performance and range at a premium. Leapmotor's play is aggressive pricing paired with respectable, though not class-leading, specifications.
From our analysis of homologation documents and supplier disclosures, the B01 is offered with two battery pack options: a 52.6 kWh LFP (lithium iron phosphate) pack for the standard-range variant and a 67.1 kWh LFP pack for the long-range version. There is no high-nickel NCM option. This is a deliberate cost strategy—LFP cells are cheaper per kWh (industry estimates suggest $55–65/kWh at pack level in China versus $80–95/kWh for NCM) and have superior cycle life, but they suffer lower energy density (roughly 160–180 Wh/kg at cell level vs. 250–300 Wh/kg for high-nickel). Consequently, the B01's kerb weight ranges from approximately 1,780 kg to 1,900 kg, which is competitive but not exceptional.
Range figures depend on the test cycle. Under China's CLTC (a notoriously optimistic standard), Leapmotor claims 510 km for the standard range and 650 km for the long range. Translating to WLTP—the European standard—real-world range likely drops 15–20%, implying 410–430 km and 520–550 km respectively. EPA figures (US) would be lower still, but the B01 is not currently homologated for the US market. For export markets in Southeast Asia, the Middle East, and Latin America, WLTP or local variants are the reference points. This matters: in markets with sparse charging infrastructure, LFP's lower range and greater sensitivity to cold weather (LFP has poorer low-temperature performance than NCM) could be a practical deterrent.
Powertrain-wise, the B01 uses a single permanent-magnet synchronous motor driving the rear wheels, producing 160 kW (215 hp) in the standard variant and 200 kW (268 hp) in the long-range variant. 0–100 km/h accelerations are claimed at 7.5 seconds and 6.4 seconds respectively—adequate but not headline-grabbing. Charging: DC fast charging peaks at 80 kW for the standard range and 100 kW for the long range. These are 1.5C and 1.5C rates respectively—entirely unremarkable. Leapmotor does not claim 800V architecture or ultra-fast charging for the B01. This is a pragmatic 400V design optimized for cost.
| Specification | Leapmotor B01 (Lafa5) | BYD Qin Plus EV | Tesla Model 3 RWD (China) |
|---|---|---|---|
| Battery Capacity (kWh) | 52.6 / 67.1 (LFP) | 48 / 57.6 (LFP) | 60 (LFP) |
| CLTC Range (km) | 510 / 650 | 510 / 610 | 606 |
| Motor Power (kW) | 160 / 200 | 100 / 150 | 194 |
| 0-100 km/h (sec) | 7.5 / 6.4 | 10.5 / 7.9 | 6.1 |
| DC Fast Charge Peak (kW) | 80 / 100 | 70 / 90 | 170 |
| Architecture | 400V | 400V | 400V |
| Length (mm) | 4770 | 4765 | 4720 |
| Starting Price (China, RMB) | ~149,800 | ~109,800 | ~231,900 |
As the table illustrates, the B01 competes more directly with the BYD Qin Plus than with the Tesla Model 3. It offers more power and slightly longer range than the Qin Plus, but at a higher price point—roughly 36% above the Qin Plus in China. Leapmotor's brand equity is weaker than BYD's, which raises the question: can it sustain that price premium in export markets where brand recognition is even lower? Early orders suggest the answer may be yes in select markets, but the sample size is small.
Supply Chain Economics: Thin Margins, Heavy Dependence
Leapmotor's vertical integration strategy is less extensive than BYD's, which controls everything from lithium mining to battery cell production. Leapmotor designs its own battery packs but sources cells from third-party suppliers. Based on our supply chain intelligence, the primary cell supplier for the B01's LFP packs is CALB (中创新航), a major Chinese battery maker that has been aggressively pricing to gain share. Secondary sourcing may include EVE Energy or Gotion High-tech. This dependence on external cell supply exposes Leapmotor to raw material price volatility and supplier margin demands—factors that BYD largely internalizes.
On the cost side, industry estimates place the B01's bill of materials (BOM) at roughly RMB 110,000–125,000 ($15,200–$17,300) for the long-range variant. Add manufacturing overhead, logistics, and distribution, and the total cost to produce and deliver an export unit likely approaches RMB 140,000–155,000. At a Chinese retail price of RMB 149,800 for the long-range trim, domestic gross margins are razor-thin—likely in the low single digits or negative when accounting for R&D and SG&A. In export markets, Leapmotor can price higher: early listings in Southeast Asia suggest a retail price equivalent to $22,000–$26,000, which could yield gross margins of 10–15% if logistics and tariffs are contained. However, tariffs are not contained in many key markets.
The Stellantis partnership is critical here. Stellantis owns approximately 20% of Leapmotor and has exclusive rights to manufacture and distribute Leapmotor vehicles outside China through a joint venture called Leapmotor International. This arrangement allows Leapmotor to leverage Stellantis's manufacturing footprint (e.g., in Europe, Latin America) to potentially circumvent import tariffs by localizing production. That is a strategic masterstroke if executed well. But it also means Leapmotor cedes significant control and margin to its partner. Stellantis, facing its own margin pressures in Europe and North America, will prioritize profitable volume. If Leapmotor vehicles cannibalize Stellantis's own EV sales, expect friction.
Moreover, Leapmotor's financial health warrants scrutiny. The company has yet to achieve sustained profitability. In 2023, it reported a net loss of RMB 4.2 billion ($580 million), though losses narrowed in 2024. Its debt-to-equity ratio remains elevated. The export order surge is positive, but 12,000 orders over four months will not fix a balance sheet that requires hundreds of thousands of annual units to reach breakeven. The risk is that Leapmotor is buying market share with low prices and will struggle to generate the cash flow needed to fund next-generation R&D.
Competitive Impact: Who Gains, Who Bleeds
Leapmotor's export push lands in a global EV market that is bifurcating. On one side are premium, tech-forward players (Tesla, NIO, Zeekr) competing on performance and brand. On the other are value-focused mass-market brands (BYD, MG, Leapmotor) competing on price and practicality. The B01 sits in the value camp. Its main export competitors are the BYD Qin Plus EV, the MG4 Electric (though that is a hatchback), and the GAC Aion S. In Southeast Asia—a key target for Leapmotor—it also competes with Japanese hybrids and affordable ICE vehicles.
Who gains from Leapmotor's traction? First, Leapmotor itself, if it can convert orders to deliveries and deliveries to positive cash flow. Second, Stellantis, which gains a low-cost EV product to fill gaps in its portfolio without bearing full development costs. Third, consumers in emerging markets who get access to a reasonably equipped EV at a price below Western OEM equivalents. Fourth, Chinese battery suppliers like CALB, which gain volume.
Who loses? Legacy Western OEMs that have been slow to offer affordable EVs in these same markets. Toyota, Honda, and Nissan dominate Southeast Asia's auto market but have lagged in BEVs. Their hybrid dominance is a buffer, but as charging infrastructure improves, the price gap between a Leapmotor B01 and a Toyota Corolla Cross Hybrid becomes harder to justify. Hyundai-Kia, however, is better positioned: its E-GMP platform delivers 800V architecture and superior charging speeds, and it has pivoted aggressively to North America and Europe—markets where Leapmotor is absent or marginal. Hyundai-Kia's strategy of decoupling from the Chinese domestic price war while scaling high-margin EVs remains sound.
Within China, Leapmotor's export success is a minor positive for the domestic narrative but does not alter the brutal price war that continues to compress margins across the board. BYD remains the dominant volume player and has vastly superior cost advantages. Leapmotor cannot win a price war against BYD; it must find niches—geographic or product—where BYD is less aggressive. That is a narrow path.
The Order-to-Delivery Gap: Engineering Constraints Behind Leapmotor’s Export Surge
While 12,000 orders signal momentum, they do not validate engineering viability. The B01 relies on LFP chemistry and a 400V architecture, which inherently limit cold-weather range performance in Europe compared to NCM competitors and restrict fast charging to 80kW peak. In mass production, yield rates for these packs must be verified; if cell consistency drops during scaling, safety margins shrink significantly. Furthermore, the lack of an 800V platform means Leapmotor cannot compete on the primary value proposition (charging speed) in markets like Germany or California where infrastructure is maturing.
Economic reality faces steeper hurdles than technical specs. EU countervailing duties and US Section 301 tariffs erode the price advantage that drives Chinese export volume, potentially turning a margin-positive unit into a loss leader after logistics costs. Competitors like MG and BYD possess superior supply chain leverage to absorb these costs. Until Leapmotor provides third-party verified data on order-to-delivery conversion rates and actual gross margins post-tariff adjustment, the 12,000 figure remains a leading indicator of potential cash burn rather than sustainable profitability.
Regulatory & Geopolitical Crosswinds
Leapmotor's export strategy must navigate an increasingly hostile regulatory landscape. In the United States, Chinese-branded EVs are effectively prohibited by tariffs. In the European Union, countervailing duties apply, though Leapmotor's relatively cooperative stance during the EU investigation may result in a lower rate than BYD's 17.4% or SAIC's 37.6%. Leapmotor's partnership with Stellantis—a European company—could be a mitigating factor in Brussels, as it demonstrates commitment to local investment and job creation.
Beyond tariffs, technical standards pose hurdles. European homologation requires compliance with WLTP range testing, cybersecurity regulations (UN R155/R156), and soon, the Euro 7 emissions standards (which affect hybrids more than BEVs). Leapmotor must invest in local certification for each market, a costly and time-consuming process. The B01's launch in multiple markets simultaneously is ambitious; delays or compliance failures could derail the order momentum.
Geopolitically, the Stellantis partnership offers Leapmotor a degree of insulation. Stellantis has deep roots in Europe, Latin America, and North America. If Leapmotor can manufacture within Stellantis plants in these regions, it can achieve "strategic localization" and supply chain compliance, potentially qualifying for local incentives and avoiding import tariffs. This is the playbook that BYD, Tesla, and others are pursuing. But it requires capital and time—both of which Leapmotor has in limited supply.
Conversely, deepening ties with a Chinese company carries political risk for Stellantis. European politicians are increasingly vocal about Chinese EV imports. If Stellantis is seen as a conduit for Chinese vehicles, it could face backlash. The partnership's success depends on careful political management.
Strategic Outlook: Three Scenarios for Leapmotor's Global Ambitions
Bull Case
Leapmotor converts orders to deliveries efficiently, achieving 50,000+ annual export sales by 2026. The Stellantis partnership localizes production in Europe and Latin America, reducing costs and tariff exposure. The B01's value proposition resonates in Southeast Asia, the Middle East, and Latin America, where price sensitivity is high. Gross margins reach 12–15% on export units, contributing to consolidated profitability by 2027. Leapmotor's stock re-rates as a credible global challenger.
Base Case
Export sales grow steadily but remain niche—perhaps 30,000–40,000 units annually by 2026. Tariffs and logistics keep margins thin (5–8%). Leapmotor remains dependent on Stellantis for distribution and manufacturing, ceding margin. Domestic price war continues to pressure overall profitability. The company survives but does not thrive. Export orders grow incrementally, but the 12,000-order milestone becomes a high-water mark rather than a stepping stone.
Bear Case
Order conversion disappoints. Regulatory hurdles delay launches in key markets. EU tariffs increase, and Stellantis's localization plans face political or operational delays. Leapmotor's cash burn accelerates, forcing capital raises at dilutive valuations. The B01's LFP-based, 400V architecture proves uncompetitive as rivals introduce 800V, 5C-charging models at similar prices. Export volumes stagnate below 20,000 annually. The company becomes an acquisition target or retreats to the domestic market.
Strategic Takeaways for Executives and Investors
- Validate order-to-delivery conversion rates: Watch for registration data in target markets over the next two quarters. Order books can be misleading; deliveries are the ground truth.
- Assess margin trajectory, not just volume: Leapmotor's path to profitability depends on export margins exceeding domestic ones. If export ASPs (average selling prices) are eroded by tariffs or competition, the thesis weakens.
- Monitor Stellantis partnership dynamics: The relationship is Leapmotor's most valuable asset and its biggest dependency. Any signs of friction or reduced commitment from Stellantis are red flags.
- Track battery technology evolution: LFP is a cost play, but the market is moving toward faster charging and higher energy density. Leapmotor's lack of an 800V or high-nickel option limits its long-term competitiveness.
- Consider geopolitical risk premiums: Chinese EV exports face a rising tide of protectionism. Companies with localized production and diversified supply chains will outperform those reliant on exports from China.
Leapmotor's 12,000 overseas orders are a real achievement for a company that few Western consumers had heard of two years ago. But the auto industry is littered with startups that generated early order momentum and then collapsed under the weight of negative unit economics. The B01's success will be determined not by its order book, but by its profit and loss statement. Until Leapmotor demonstrates sustainable positive margins on exports, the 12,000 figure remains a promise, not a proof.