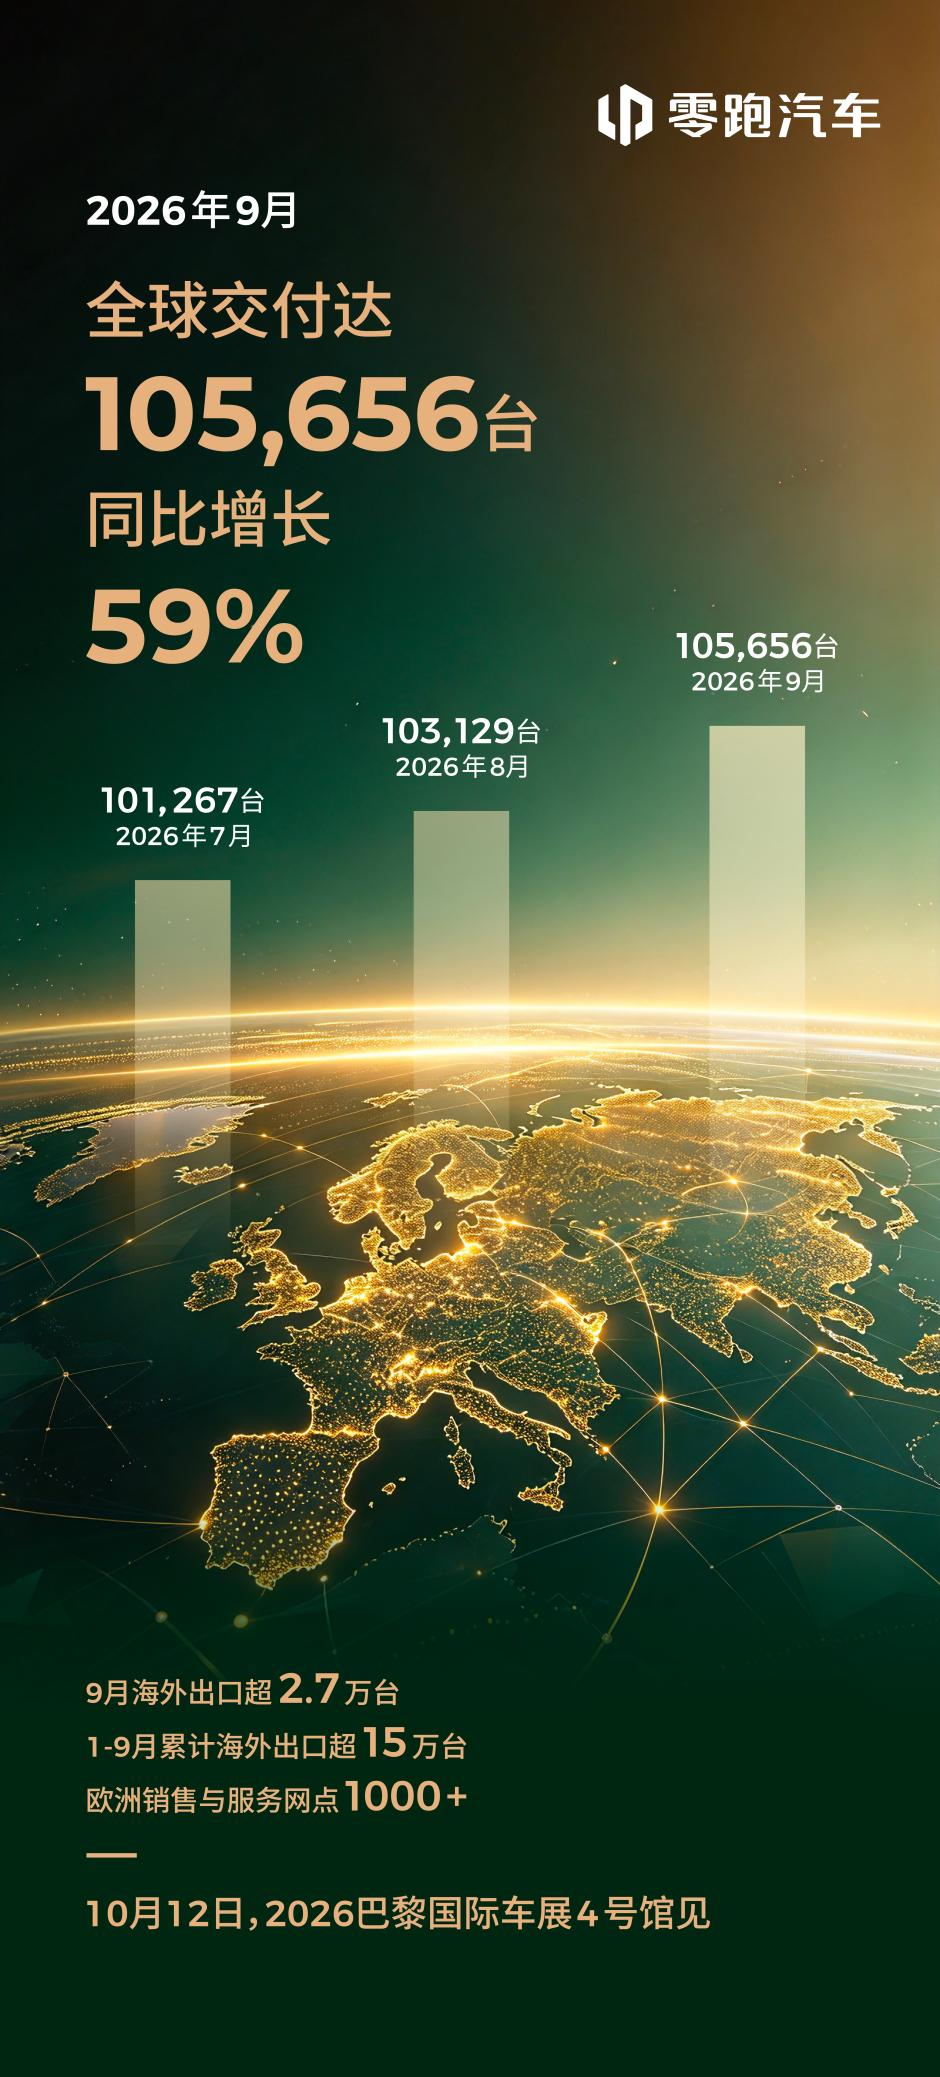
When Leapmotor reported September global deliveries of 105,656 units—marking a 59% year-on-year surge and cementing consecutive months above the six-figure threshold—financial headlines across Frankfurt, Paris, and Detroit framed it as an unequivocal triumph for cross-border collaboration. Through its joint venture with European automotive titan Stellantis, Leapmotor has ostensibly established an operational blueprint for how high-tech, low-cost Chinese electric architectures can permeate Western markets. Yet beneath this record-breaking volume lies a complex structural tension between hyper-competitive Chinese manufacturing costs, razor-thin operating margins, and the geopolitical fortifications of the European Union.
Historically, emerging Chinese new energy vehicle (NEV) startups faced a binary strategic dilemma: burn capital on aggressive direct overseas retail networks—as NIO and XPeng attempted with mixed success in Northern Europe—or remain trapped within China’s margin-crushing domestic market. Leapmotor disrupted this paradigm in late 2023 when Stellantis acquired an approximate 20% equity stake for roughly €1.5 billion ($1.6 billion), establishing Leapmotor International—a 51:49 Stellantis-led joint venture holding exclusive export and manufacturing rights outside Greater China. The September delivery milestone validates this distribution engine, but it also elevates fundamental questions regarding actual operating economics, technology sovereignty, and local European supply chain compliance.
The LEAP 3.5 Architecture: Engineering Teardown and Western Counterparts
Leapmotor’s explosive delivery acceleration relies on its in-house developed modular architecture, currently embodied in its 'Four-Leaf Clover' centrally controlled domain architecture and LEAP 3.0/3.5 platform. Unlike legacy platforms requiring dozens of distributed Electronic Control Units (ECUs), Leapmotor consolidates cockpit, intelligent driving, body, and vehicle domain controllers into a single integrated System-on-Chip (SoC) compute platform. In models like the C16 multi-purpose SUV and C10 crossover, Leapmotor pairs Qualcomm Snapdragon 8295 digital cockpit silicon with Orin-X autonomous driving chips, delivering an entry-level computing baseline of up to 254 TOPS at price points that baffle Western product planners.
On the powertrain front, Leapmotor leverages cell-to-chassis (CTC) 2.0 battery packaging, integrating the battery cell modules directly into the underbody structure to maximize structural rigidity by 25% and reduce total curb weight. The brand utilizes both extended-range electric vehicle (EREV) configurations and pure battery electric (BEV) setups. The pure electric C10 utilizes an 800V silicon carbide (SiC) high-voltage platform capable of peak charging rates up to 2.4C, delivering a 30% to 80% state-of-charge (SoC) replenishment in approximately 18 minutes. In contrast, the European-spec Leapmotor T03 urban compact retains a 400V architecture and a modest 37.3 kWh Lithium Iron Phosphate (LFP) pack, deliberately tailored for entry-level B-segment affordability.
| Metric / Specification | Leapmotor C10 (LEAP 3.0) | Volkswagen ID.4 (MEB) | Kia EV6 (E-GMP) | BYD Atto 3 (e-Platform 3.0) |
|---|---|---|---|---|
| Primary Architecture | Central Domain (800V SiC / CTC) | Distributed Domain (400V) | Dedicated 800V SiC (E-GMP) | Cell-to-Body (CTB, 400V) |
| Battery Chemistry / Capacity | LFP / 69.9 kWh | NCM 712 / 77.0 kWh | NCM 811 / 77.4 kWh | LFP Blade / 60.5 kWh |
| Peak Fast-Charging Rate | 2.4C (up to 180 kW) | 1.7C (up to 135 kW) | 4.5C (up to 235 kW) | 1.5C (up to 88 kW) |
| 10-80% Charging Time | ~18-20 minutes | ~28 minutes | ~18 minutes | ~29 minutes |
| Compute / Autonomous Baseline | 1x Orin-X (254 TOPS) + Lidar | Mobileye EyeQ4 / Travel Assist | Hyundai ADAS / Radar-Vision | DiPilot / Radar-Vision (8 TOPS) |
| Domestic Base Price (CNY / USD) | RMB 128,800 (~$17,800) | RMB 149,800 (~$20,700) | RMB 179,800 (~$24,800) | RMB 119,800 (~$16,500) |
| European Target Retail Price | €36,400 (~$39,800) | €40,335 (~$44,100) | €44,990 (~$49,200) | €37,990 (~$41,500) |
As the comparative data illustrates, Leapmotor bridges a critical capability gap. It provides architectural sophistication approaching South Korea’s dedicated 800V platforms (such as Hyundai-Kia's E-GMP) while undercutting European legacy OEM price benchmarks by 10% to 20%. However, achieving this balance on paper is vastly different from maintaining it through sustained, severe road testing and long-term durability across global climate zones.
Supply Chain Realities: Deep Tier-1 Integration vs. BOM Cost Arbitrage
Leapmotor repeatedly touts an extraordinary 60% internal development rate across its total Bill of Materials (BOM), claiming to produce its own e-powertrain assemblies, central processing unit motherboards, and integrated lighting systems. Yet, an objective teardown of their primary supply tier reveals reliance on established institutional suppliers alongside hyper-optimized domestic Chinese vendors. For battery cells, Leapmotor primarily sources prismatic LFP chemistries from CALB (China Aviation Lithium Battery) and Gotion High-tech, while higher-tier configurations historically drew from CATL. By dual-sourcing across CALB and Gotion, Leapmotor commands pack-level procurement costs estimated at roughly $62 to $68 per kWh—a level Western OEMs producing in North America or Europe cannot match due to local raw material processing deficits.
For high-performance semiconductors and intelligent driving sensors, the dependency swings outward. While domestic Chinese silicon vendors such as Horizon Robotics have made inroads, Leapmotor relies on Nvidia (Orin-X) for compute processing in high-spec models and Qualcomm (SA8155P and SA8295P) for smart cockpit telemetry. Tier-1 chassis components, braking controllers, and dynamic stability systems feature partnerships with Bosch and Continental, heavily localized within their Chinese production facilities. This hybrid sourcing structure affords Leapmotor massive domestic cost arbitrage inside China, but introducing these components into Western production channels creates complex logistics, component customs valuation, and warranty risk allocations between Leapmotor and Stellantis.
Competitive Repercussions: Squeezing the Mass-Market Core
Leapmotor’s global scale fundamentally disrupts three distinct automotive cohorts. First, European mass-market legacy brands—including Renault, Volkswagen, and even Stellantis’s own internal brands like Fiat and Opel—face structural cannibalization. By importing the budget T03 compact and C10 SUV via Stellantis's established European dealer network of over 350 franchise points, the joint venture introduces a pricing benchmark that undermines native European BEV programs burdened by high domestic labor and energy costs.
Second, domestic Chinese rivals such as BYD, Geely, and Chery face a formidable export adversary. While BYD must invest billions of dollars to construct greenfield distribution networks, roll-on/roll-off (Ro-Ro) shipping fleets, and retail concessions across Europe, Leapmotor plugged directly into Stellantis’s mature distribution, logistics, and parts replenishment infrastructure virtually overnight. This asset-light global deployment reduces Leapmotor’s upfront operational expenditure.
Conversely, completely decoupled global players—most notably Hyundai Motor Group—maintain a distinct defensive moat. Having strategically reduced their domestic Chinese footprint, Hyundai and Kia remain largely unexposed to the ongoing Chinese retail price war. With platforms like E-GMP already producing robust operating margins across the United States, Europe, and India, these decoupled OEMs are competing on mature lifecycle reliability, superior fast-charging curves (sustained 4.5C charging rates), and uncompromised regulatory compliance, rather than engaging in a race to the bottom on retail sticker price.
The Reality Check: Volume Records vs. Economic and Physical Realities
The headline metric—delivering 105,656 units in a single month—demands rigorous interrogation. In the automotive industry, top-line delivery numbers frequently obscure underlying financial vulnerabilities. Leapmotor has spent years operating with razor-thin or negative gross margins, heavily impacted by the brutal price war orchestrated by BYD within mainland China. While gross margins turned modestly positive in late 2023, reaching low single-digit figures, the company’s net bottom line has historically remained deeply constrained by marketing overhead, price cuts, and continuous R&D amortization.
- The LFP Chemistry Wall: The heavy reliance on LFP cells enables Leapmotor to hit aggressive entry price points, but LFP suffers from severe electrochemical limitations. In cold European winter conditions (sub-zero Celsius), usable battery capacity and discharge efficiency can degrade by 30% to 40%, accompanied by significantly degraded DC fast-charging acceptance. Western consumers accustomed to steady highway cruising and predictable winter ranges may find real-world LFP performance substantially below WLTP estimates.
- The Contract Manufacturing Illusion: Stellantis has initiated plans to assemble the Leapmotor T03 using semi-knocked-down (SKD) kits at its Tychy assembly plant in Poland. However, SKD assembly is an operational stopgap, not an enduring competitive panacea. It remains vulnerable to supply chain disruptions, geopolitical scrutiny, and changing European rules of origin. Moving to complete local manufacturing (CKD) with genuine European supply chain depth would immediately erase a substantial portion of Leapmotor’s low-cost labor and bill-of-materials cost advantage.
- Software Localization and Regulatory Friction: Chinese-market human-machine interfaces (HMI) and ADAS systems excel in heavily mapped, geofenced Chinese mega-cities. Transferring these software-defined features to Western Europe requires massive code refactoring to comply with the European Union's General Data Protection Regulation (GDPR) and UNECE cybersecurity frameworks (R155 and R156). Advanced driver assistance features that function seamlessly in Hangzhou often struggle when confronting poorly marked European rural roads, stringent Euro NCAP edge cases, and local language localization.
Geopolitical and Regulatory Minefields
The regulatory backdrop for Leapmotor’s European expansion is fraught with policy risks. The European Commission’s finalized countervailing duties on battery electric vehicles imported from China impose definitive tariffs ranging from 17% to over 35% on top of the standard 10% import duty. For Leapmotor, vehicles manufactured in China and exported directly to the EU face substantial duty burdens that eliminate their traditional retail margin buffer.
While the joint venture aims to circumvent direct import tariffs by utilizing Stellantis's manufacturing footprint in Poland or other European facilities, European regulators are already scrutinizing 'screwdriver factories.' Under tightening rules of origin regulations, vehicles assembled from imported Chinese battery packs, structural sub-assemblies, and high-value electronics could still face punitive duties or regulatory disqualification from national EV purchase incentives (such as France’s eco-score incentive scheme). For institutional investors, assuming that joint-venture SKD production offers a friction-free workaround to Western industrial policy is an oversimplification of trade compliance realities.
Strategic Outlook and Investor Implications
As Leapmotor expands its footprint beyond 100,000 monthly deliveries and accelerates international customer handovers, market participants must monitor three divergent trajectories over the next 24 to 36 months.
Bull Case
Stellantis successfully scales localized SKD and CKD assembly in Tychy and Southern Europe, achieving complete compliance with EU local-content requirements. Leapmotor captures a 5% to 8% market share in Europe’s entry-to-mid BEV segments, successfully shielding itself from punitive tariffs. Domestic Chinese gross margins stabilize above 12% as supply chain scale amortizes R&D costs, turning the company sustainably net-profitable by 2026.
Base Case
European sales grow steadily but remain capped by regulatory scrutiny, requiring Stellantis to source more expensive European Tier-1 battery cells and power electronics. This dynamic erodes Leapmotor’s cost advantage, forcing European retail pricing up into direct competition with Volkswagen and Renault. Domestic Chinese volumes remain strong above 90,000 to 110,000 units monthly, but continuous domestic price cuts keep overall corporate operating margins hovering near break-even.
Bear Case
The European Union tightens rules of origin and foreign subsidy scrutiny on assembly kits, effectively neutralizing the Tychy manufacturing bypass and subjecting Leapmotor vehicles to full tariff structures. Simultaneously, escalating domestic price competition in China forces further margin erosion, while brand fragmentation and software localization bugs damage initial customer satisfaction scores in Europe, resulting in inventory buildup and stranded assembly capacity.
- Asset-Light Strategy Is Validated, But Constrained: Leveraging Stellantis provides Leapmotor with unmatched overseas distribution velocity, yet the model remains structurally tethered to shifting EU trade compliance definitions.
- Margin Quality Over Delivery Quantity: Institutional equity analysts must look beyond top-line delivery milestones of 100,000+ units and rigorously interrogate operating cash flow, R&D capitalization rates, and realized net margins per vehicle.
- Chemical Architecture Trade-offs: High reliance on LFP battery packs supports initial price competitiveness but introduces real-world winter performance friction in premium and Western export markets.
- Decoupled OEMs Maintain High-Margin Moats: Automakers like Hyundai-Kia, which have minimized direct exposure to Chinese domestic price deflation while mastering 800V engineering, offer a more resilient hedge against trade friction and margin compression.
