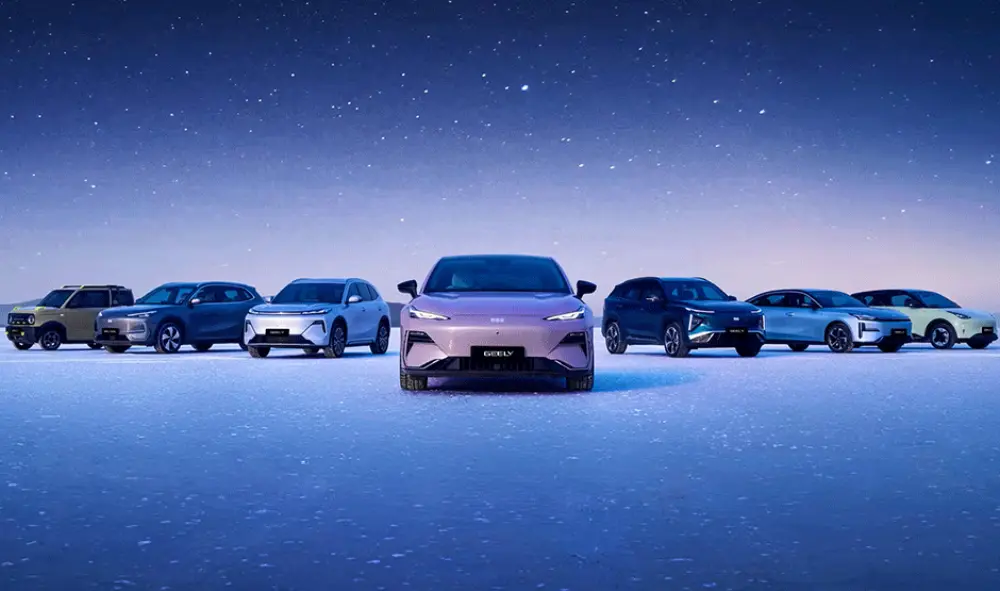
When Geely Auto Group formally announced its commercial entry into Canada on October 9, the move sent shockwaves through North American automotive policy circles. Just weeks earlier, Ottawa had formally mirrored Washington by ratifying a punitive 100% surtax on Chinese-manufactured battery electric vehicles (BEVs), alongside a 25% tariff on steel and aluminum imports. For an OEM headquartered in Hangzhou to deliberately plant its corporate flag north of the 49th parallel during the most intense wave of Western protectionism in four decades is neither an administrative afterthought nor a reckless gamble. It represents an aggressive stress-test of North American trade boundaries, executed by China’s most structurally diversified automotive conglomerate.
Historically, Chinese passenger car brands have treated the North American market with deep hesitation, chastened by the regulatory hurdles, litigious distribution landscapes, and stringent Federal Motor Vehicle Safety Standards (FMVSS) and Canadian Motor Vehicle Safety Standards (CMVSS). While competitors like BYD paused their immediate Canadian consumer launch explorations following Ottawa’s August tariff declarations, Geely’s decision to move forward reveals a fundamentally divergent calculus. Rather than retreating into domestic price wars or confining overseas ambitions to Southeast Asia, the Middle East, and Latin America, Geely is leveraging its vast multi-brand ecosystem—honed through decades of integrating European acquisitions—to carve out a resilient commercial foothold in North America.
The Powertrain Playbook: Bypassing the Pure Electric Surtax
The central paradox of the Geely Canadian market expansion lies in the product slate itself. Western observers routinely conflate Chinese automotive globalization with pure battery-electric vehicle exports. However, scrutinizing Canada’s regulatory tariff schedule reveals an immediate tactical opening: the 100% surtax applies explicitly to battery electric vehicles under tariff item 8703.80. Plug-in hybrid electric vehicles (PHEVs) and conventional hybrid powertrains (HEVs) fall under distinct Harmonized System (HS) classifications, retaining the standard Most-Favoured-Nation (MFN) tariff rate of approximately 6.1% unless Ottawa enacts supplemental trade sanctions.
Geely Auto Group possesses one of the industry’s most sophisticated electrified hybrid powertrain portfolios, anchored by its NordThor (Leishen Power) architecture. The NordThor 2.0 system integrates a dedicated hybrid engine boasting thermal efficiency figures exceeding 46%, paired with a 3-speed dedicated hybrid transmission (DHT) and dual-motor P1/P2/P3 configurations. By leading its Canadian distribution strategy with extended-range or plug-in hybrid options—such as the Monjaro (Xingyue L) hybrid or the Galaxy series PHEV SUVs—Geely can offer Canadian buyers fuel economy exceeding 4.5 L/100 km and over 1,200 kilometers of combined range at a pricing tier that legacy domestic OEMs cannot match, completely sidestepping the punitive BEV duty.
| Metric / Architecture | Geely Galaxy L7 (NordThor PHEV) | Toyota RAV4 Prime (PHEV) | Ford Escape Plug-In Hybrid | BYD Song Plus DM-i (Global Spec) |
|---|---|---|---|---|
| Engine Thermal Efficiency (%) | 46.1% (BHE15-BFZ) | 41.0% (Dynamic Force 2.5L) | 40.0% (2.5L Atkinson-Cycle) | 46.06% (Xiaoyun 1.5L) |
| Transmission Configuration | 3-Speed DHT Pro (Dual-Motor) | e-CVT (Power Split Planetary) | e-CVT (Planetary) | EHS Single-Speed Direct-Drive |
| Battery Capacity & Chem. | 18.7 kWh LFP (Aegis Shield) | 18.1 kWh Ternary NCM | 14.4 kWh Ternary NCM | 18.3 kWh Blade LFP |
| Pure Electric Range (WLTP/EPA) | 90 km (WLTP) | 68 km (EPA) | 60 km (EPA) | 85 km (WLTP) |
| North American Base Price Est. | $31,000 - $34,000 CAD (Target) | $50,950 CAD | $43,999 CAD | N/A (Launch Suspended) |
| Canadian Tariff Vulnerability | Standard MFN (6.1%) | Zero Tariff (CUSMA / Local) | Zero Tariff (CUSMA / US) | 100% Surtax (If BEV) / 6.1% (PHEV) |
As the comparison table illustrates, Geely’s engineering metrics allow it to match or exceed the performance parameters of entrenched Japanese and American incumbents in the compact crossover sector, while maintaining an estimated bill-of-materials advantage of 25% to 35%. This hardware delta becomes the bedrock of its commercial viability in suburban Toronto, Vancouver, and Montreal, where consumer appetite for affordable electrification remains acute despite shifting federal subsidy frameworks.
Supply Chain Architecture and the Swedish Engineering Shield
Unlike vertically integrated monoliths such as BYD, which rely heavily on internal component divisions like FinDreams, Geely operates a distributed, highly globalized tier-1 procurement matrix. This network was constructed following the 2010 acquisition of Volvo Car Corporation and subsequent joint ventures with Renault (Horse Powertrain Limited). This hybrid supply chain architecture is the cornerstone of the Geely Canadian market expansion, providing both technical credibility and crucial regulatory insulation.
In safety and structural engineering, Geely utilizes the Compact Modular Architecture (CMA), jointly developed with Volvo at the China Euro Vehicle Technology (CEVT) center in Gothenburg, Sweden. The CMA platform powers vehicles across multiple corporate divisions, including the Volvo XC40, Lynk & Co crossovers, and Geely Auto’s flagship domestic models. For the Canadian market, this shared lineage is indispensable. Achieving CMVSS homologation—particularly regarding dynamic crash testing, roof-crush structural rigidity under CMVSS 216, and cold-weather electronic stability programming under CMVSS 126—is substantially de-risked because the underlying chassis architecture has already cleared North American validation under Volvo badges.
On the component level, Geely draws heavily on Western tier-1 suppliers already operating within North American logistics corridors. Key systems include:
- Braking and Chassis Control: Bosch Generation 9.3/Integrated Power Brake (IPB) systems and Continental electronic stability modules.
- Silicon Carbide & Inverters: Strategic supply agreements with STMicroelectronics and Rohm Semiconductor for 800V and high-voltage DC-DC conversion hardware.
- Infotainment & Cockpit Compute: Silicon designed by SiEngine (SE1000 'DragonHawk One' 7nm automotive cockpit SoC), backed by Geely’s ECARX ecosystem, complemented by Qualcomm Snapdragon 8155/8295 platforms engineered for global software stacks.
- Battery Cells: Pack-level assembly via VREMT (Viridi E-Mobility Technology), utilizing cell chemistry sourced from CATL and CALB, with advanced cold-weather liquid thermal management systems calibrated for Nordic and Canadian sub-zero winters.
By relying on globalized tier-1 systems rather than a strictly insular domestic supply chain, Geely minimizes operational friction when servicing vehicles across Canadian metropolitan centers, ensuring localized parts accessibility through third-party logistics networks.
Competitive Impact Across North American Dealerships and Automakers
The geopolitical reality facing automotive executives in Detroit and Tokyo is that the Canadian border cannot be entirely insulated from technological price deflation. The Geely Canadian market expansion presents asymmetrical challenges across three distinct industry cohorts:
1. Detroit Legacy Automakers (GM, Ford, Stellantis)
The Big Three have largely abandoned entry-level sedans and compact sub-$35,000 crossovers in North America, pivoting almost exclusively toward high-margin full-size pickup trucks and large three-row SUVs. This strategic retreat has created a vast affordability void in the Canadian retail landscape, where household disposable incomes have lagged US benchmarks and vehicle financing rates hover above 7%. If Geely establishes an independent franchise network or leverages multi-brand distribution partners offering well-equipped hybrid crossovers under $35,000 CAD, Detroit will face structural market-share erosion in urban Canadian markets without possessing an immediate product response.
2. Japanese Hybrid Incumbents (Toyota, Honda)
Toyota currently dominates the Canadian hybrid landscape, enjoying waitlists extending from 6 to 18 months for models like the RAV4 Hybrid and Sienna. Geely’s entrance targets this specific supply shortfall. If Geely can deliver comparable real-world fuel economy and European-influenced driving dynamics with immediate dealer allotment availability, it will siphon off pragmatic suburban buyers who are weary of dealer markups and multi-year order backlogs.
3. European Premium Brands and Sister Marque Cannibalization
Within Geely’s own corporate constellation, strategic boundary lines must be rigorously enforced. Geely Auto must position itself strictly as a mainstream value-technology brand to prevent brand cannibalization of Polestar and Volvo. Furthermore, European importers like Volkswagen, which have struggled to bring competitive mass-market PHEVs to North America, face severe pricing pressure from a Chinese OEM that has mastered low-cost software integration and high-speed feature iteration.
The Reality Check: Cold-Weather Physics, Distribution Deficits, and Political Backlash
Behind the corporate press announcements, the operational hurdles facing Geely in Canada are severe. Independent industry analysts must look past the polished marketing narratives to evaluate the formidable commercial and physical constraints that could derail this initiative.
1. The Sub-Zero Operational Penalty
Canada is an unforgiving proving ground for electrified powertrains. In regions like Alberta, Saskatchewan, and northern Ontario, winter ambient temperatures regularly plunge below -25°C. At these extremes, lithium-iron-phosphate (LFP) battery chemistries suffer catastrophic ionic conductivity drops, leading to lithium plating risks during fast-charging, severe regenerative braking curtailment, and cabin-heating energy penalties that can slash total driving range by 40% to 55%.
While Geely touts its Aegis battery safety testing and intelligent pulse self-heating algorithms, real-world cold-weather durability across salted road networks presents severe engineering challenges. Accelerated galvanic corrosion from calcium chloride road treatments, high-voltage harness insulation degradation, and heat-pump coefficient of performance (COP) collapse below -20°C remain unverified in long-term Canadian consumer field cycles.
2. The Retail and Aftersales Distribution Desert
Establishing an automotive brand from scratch in Canada requires tens of millions of dollars in capital expenditure for brick-and-mortar dealer networks, certified warranty service bays, and centralized spare-parts warehousing in Ontario or Quebec. Unlike legacy competitors with hundreds of established touchpoints, Geely enters Canada with zero proprietary retail footprint. If it attempts an asset-light direct-to-consumer agency model—similar to early Tesla or Polestar deployments—it will confront immense resistance regarding warranty processing, local trade-in evaluations, and immediate mechanical repairs, particularly outside the Vancouver and Toronto metropolitan corridors.
3. The CUSMA Policy Whiplash
Perhaps the most acute vulnerability is political risk. Section 301 tariffs in the United States and Canada's parallel surtaxes are designed not merely to balance trade ledgers, but to completely prohibit Chinese automotive supply chains from establishing a perimeter around the North American industrial base. If Geely begins capturing meaningful retail volume through hybrid tariff exemptions, Ottawa will face immense pressure from the United States Trade Representative (USTR) during the upcoming 2026 CUSMA/USMCA joint review to close the hybrid loophole and classify all vehicles from Chinese parent entities under punitive surtax regimes regardless of powertrain chemistry.
The Trade and Regulatory Chessboard: Local Assembly vs. Tariff Walls
To survive long-term in North America, the Geely Canadian market expansion must evolve beyond simple finished-vehicle (CBU) shipping. Western trade policy is actively shifting toward total supply chain traceability, focusing on rules of origin, critical mineral sourcing, and software sovereignty.
Washington’s proposed Department of Commerce rules prohibiting Chinese-developed connected vehicle software and hardware modules (V2X, automated driving perception algorithms, and telematics units) will inevitably influence Canadian telematics standards. Canada cannot afford to become an unaligned software backdoor into North American critical infrastructure. Consequently, Geely must ensure that its Canadian-market vehicles operate on fully localized software stacks, with data hosted on Western cloud infrastructure (such as AWS Canada or Microsoft Azure) and operating systems completely separated from domestic Chinese server infrastructure.
Furthermore, Geely's ultimate countermeasure to the 100% tariff wall involves industrial restructuring. Through Horse Powertrain Limited—its 50-50 powertrain joint venture with Renault—and its minority ownership stakes in international assembly assets, Geely possesses the theoretical blueprint to route complete knock-down (CKD) or semi-knock-down (SKD) kits through neutral jurisdictions. If vehicle final assembly occurs in a facility complying with CUSMA Regional Value Content (RVC) mandates—requiring 75% North American core parts content—Geely could legally bypass import surtaxes entirely. However, achieving 75% local content without access to North American unionized stamping, casting, and battery manufacturing facilities remains an immense, near-insurmountable hurdle over the next three to five years.
Strategic Outlook: Three Scenarios for Geely in North America
How the Geely Canadian market expansion unfolds over the remainder of the decade depends on regulatory retaliation, consumer adoption, and internal capital allocation. Industry strategists and equity analysts should model three distinct pathways:
Bull Case: The Hybrid Niche Pioneer
Geely successfully exploits Canada’s powertrain tariff differential by launching exclusively with high-efficiency PHEVs and hybrid crossovers priced 20% below comparable Japanese models. Leveraging Canadian multi-brand dealer conglomerates eager for inventory volume, Geely secures 40 retail locations across British Columbia, Ontario, and Quebec within 24 months. By hosting telematics data locally and demonstrating robust cold-weather battery management, Geely achieves steady annual deliveries of 12,000 to 18,000 units, capturing healthy operational margins while avoiding retaliatory regulatory action ahead of the 2026 CUSMA review.
Base Case: Regulatory Attrition and Modest Regional Foothold
Geely establishes a presence limited primarily to urban Vancouver and Toronto, but faces intense bureaucratic friction regarding CMVSS compliance audits and import customs documentation. Public skepticism regarding Chinese manufacturing origin dampens residual values, keeping retail demand modest. Ottawa, under diplomatic pressure from Washington, amends its tariff definitions in late 2025 to impose an additional 25% to 35% duty on imported Chinese hybrid powertrains. Geely remains in the Canadian market with low volumes (3,000 to 5,000 units annually), treating the operation purely as an expensive listening post and technical research laboratory for North American regulatory adaptation.
Bear Case: Complete Regulatory Exclusion
Spurred by US regulatory alignment, the Canadian Department of Finance expands the 100% surtax to encompass all electrified vehicles—including PHEVs, EREVs, and HEVs—manufactured in China or produced by Chinese-controlled corporate entities overseas. Simultaneously, Ottawa institutes strict connected-car security bans matching US Department of Commerce directives, rendering Geely's infotainment and driver-assistance architectures non-compliant. Facing insurmountable tariff liabilities and prohibitive compliance costs, Geely halts consumer distribution operations in Canada, absorbing write-downs on localized homolgation investments and retreating to less politically volatile export markets.
Executive Takeaways and Investor Implications
- Powertrain Selection Dictates Tariff Viability: Geely's entry hinges on exploiting the regulatory delta between pure BEVs (subject to 100% Canadian surtaxes) and hybrid/PHEV architectures (subject to baseline 6.1% MFN tariffs), exposing Ottawa’s immediate trade policy blind spots.
- Platform Commonality Offsets Homologation Costs: By utilizing the Compact Modular Architecture (CMA) co-developed with Volvo, Geely dramatically curtails CMVSS compliance expenditures and engineering cycle times compared to other Chinese greenfield market entrants.
- Cold-Weather Physics Remain Unforgiving: Real-world consumer acceptance across Canada will be dictated by sub-zero thermal management performance; failure to address severe winter range degradation and road-salt corrosion will rapidly destroy initial brand equity.
- The CUSMA 2026 Cliff Emerges: Any commercial foothold established by Geely in Canada is subject to severe political risk. The upcoming 2026 joint trade agreement review will almost certainly target Chinese hybrid assembly, connected software components, and cross-border regulatory arbitrage.