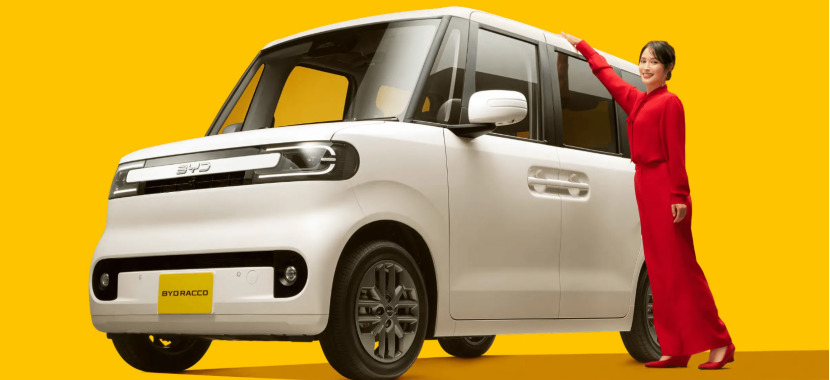
When BYD announced plans to engineer a micro-electric vehicle specifically tailored to the hyper-rigid constraints of Japan's kei-car regulations, mainstream automotive commentary treated the move as an eccentric, low-margin regional experiment. Japan's domestic market has historically served as a graveyard for foreign automakers, dominated by domestic champions like Suzuki, Daihatsu, and Nissan whose compact, tax-advantaged kei platforms dictate urban transit. However, fresh supply chain data and initial dispatch notices reveal a significantly more ambitious strategic pivot: BYD's kei-car EV platform is bypassing the borders of Japan to debut in disparate global regions, starting with Macau and Sri Lanka. This cross-border deployment signals a deliberate test of ultra-compact electric platforms across right-hand-drive (RHD) emerging economies and dense metropolitan enclaves.
Historically, kei cars—defined by strict dimensions under 3.4 meters in length, 1.48 meters in width, 2.0 meters in height, and displacement caps that electric motors translate into power limits of 47 kW (63 hp)—have remained almost entirely trapped within the Japanese archipelago. Western and emerging market distributors consistently rejected them due to crash compatibility concerns, low top speeds, and razor-thin dealer margins. Yet, as urbanization intensifies and mass-market consumers in developing nations find full-sized C-segment electric vehicles economically unattainable, BYD's kei-car EV export strategy highlights an opportunistic pivot: utilizing standardized, low-cost micro-architectures to corner neglected entry-level segments before Western or Japanese legacy OEMs can deploy cost-effective compact electric solutions.
Engineering the Sub-Compact Architecture: Battery Chemistry vs. Crash Safety
Engineering a purpose-built kei-car electric vehicle requires navigating a severe packaging compromise. Within a footprint restricted to 3,395 mm in length and 1,475 mm in width, engineers must integrate an energy storage system capable of delivering acceptable daily range while preserving structural rigidity against regional crash testing protocols. BYD has achieved this by adapting its proprietary Cell-to-Body (CTB) structural architecture to a scaled-down LFP (Lithium Iron Phosphate) Blade battery pack. Rather than relying on modular enclosures that consume precious volumetric space, the cells themselves act as structural reinforcement beams across the vehicle's floor pan.
While standard passenger EVs from BYD, such as the Seal or Dolphin, utilize battery capacities ranging from 44.9 kWh to 82.5 kWh operating on 400V or 800V bus voltages, the exported micro-EV architecture features a targeted 20 kWh to 30 kWh LFP pack. This structural chemistry limits curb weight to roughly 1,050 to 1,150 kg, enabling the vehicle to deliver an estimated WLTC range of 180 km to 220 km. The powertrain leverages an integrated 3-in-1 electric drive unit generating approximately 47 kW of maximum output, matching the statutory Japanese kei ceiling while maintaining adequate torque delivery (peaking around 130 to 160 Nm) for steep urban topographies such as Macau's historic center or Colombo's high-density traffic arteries.
| Metric / Specification | BYD Kei-Car Export Platform | Nissan Sakura (Nissan/Mitsubishi) | Wuling Hongguang MINI EV | Hyundai Inster (Casper EV) |
|---|---|---|---|---|
| Overall Length (mm) | 3,395 | 3,395 | 2,920 | 3,825 |
| Overall Width (mm) | 1,475 | 1,475 | 1,493 | 1,610 |
| Battery Capacity (kWh) | ~20 - 30 (LFP Blade) | 20.0 (Ternary NCM) | 13.9 - 26.5 (LFP) | 42.0 - 49.0 (NCM) |
| Peak Power Output (kW) | 47 (63 hp) | 47 (63 hp) | 20 - 30 (27 - 40 hp) | 71.1 - 84.5 (95 - 113 hp) |
| Architecture Voltage | ~300V - 400V | 350V | ~100V - 150V | 400V |
| DC Fast Charging Capable | Yes (CCS2 / CHAdeMO, ~30 kW) | Yes (CHAdeMO, ~30 kW) | Optional / Low Power | Yes (CCS, up to 120 kW) |
| Estimated Base Price ($ USD eq.) | $11,500 - $14,000 | $16,500 (pre-subsidy Japan) | $5,000 - $9,000 | $24,000 - $27,000 |
Thermal management in this compact category represents a technical friction point. While basic Chinese micro-EVs like the Wuling Hongguang MINI EV historically utilized passive air cooling to compress bill-of-materials (BOM) costs, BYD's export iteration implements active liquid cooling and direct refrigerant heat-pump circuits. This engineering choice is mandatory for sustained operation in tropical climates like Sri Lanka, where ambient temperatures exceeding 35 degrees Celsius degrade battery cycle life and trigger aggressive thermal throttling during repetitive urban stop-and-go driving.
Supply Chain Realities and Bill-of-Materials Decomposition
The core catalyst enabling BYD to deploy this vehicle beyond Japan lies in its vertical supply integration. Where legacy Japanese automakers must source structural cells from external joint ventures (such as Prime Planet Energy & Solutions or Envision AESC) and pay commercial integration margins, BYD manufactures virtually every primary component in-house via its FinDreams subsidiaries. Industry estimates indicate that BYD's direct cell-level manufacturing cost for structural LFP Blade packs hovers between $52 and $58 per kilowatt-hour, giving the Chinese manufacturer an immediate 25% to 35% pack-level cost advantage over ternary-equipped competitors like the Nissan Sakura.
A critical technical distinction governs the power electronics tier. While full-sized premium EVs are transitioning toward costly Silicon Carbide (SiC) MOSFET inverters to maximize high-load motor efficiency, the micro-EV platform relies entirely on mature 650V Silicon Insulated Gate Bipolar Transistors (IGBTs), fabricated internally by BYD Semiconductor. The power demands of a 47 kW permanent magnet synchronous motor do not warrant the elevated BOM cost of SiC modules. By deploying mature, depreciation-amortized 8-inch silicon wafer lines, BYD constrains the complete electronic powertrain BOM—comprising inverter, DC-DC converter, and on-board charger (OBC)—to an estimated $750 to $900 per vehicle unit.
However, regional logistics introduce friction. Adapting a vehicle originally certified for Japan to markets like Sri Lanka and Macau requires reconfiguring charging interfaces from the Japanese-standard CHAdeMO protocol to international CCS Combo 2 and GB/T standards. Additionally, right-hand-drive (RHD) component tooling—encompassing asymmetric steering racks, specialized pedal boxes, and dashboard molding—requires high upfront capital expenditure that cannot be recovered through marginal volumes in micro-economies alone. BYD's initial batches in Macau and Sri Lanka serve as low-risk proving grounds to validate RHD software stacks and regional distributor networks ahead of larger target allocations across the UK, Australia, New Zealand, and ASEAN hubs like Thailand and Malaysia.
Competitive Impact Assessment: Encroaching on Legacy Strongholds
The strategic deployment of a sub-$15,000, crash-compliant electric vehicle creates asymmetrical pressure across multiple automotive battlegrounds. The primary entity facing direct margin compression is Japan's domestic manufacturing cartel. Suzuki, Daihatsu, and Honda have historically dominated developing RHD markets across South Asia and parts of Africa by exporting inexpensive internal combustion engine (ICE) kei platforms or derived compacts (such as the Suzuki Alto and Wagon R). If BYD successfully introduces an electrified alternative with near-zero operating costs, Japanese OEMs will find their traditional market moats challenged at the lowest end of the pricing pyramid.
For Western OEMs, the immediate impact appears negligible on the surface because manufacturers like Ford, General Motors, and Stellantis abandoned the global A-segment years ago due to an inability to manufacture small vehicles profitably. However, this absence creates a structural strategic blind spot. By vacating urban micro-mobility, Western automakers allow Chinese manufacturers to cement dealer networks, customer trust, and digital ecosystem footprints in rapid-growth emerging markets. Once a consumer enters an OEM's ecosystem through an entry-level commuter car, migrating that customer to higher-margin B- and C-segment platforms becomes exponentially easier.
Conversely, within China's domestic market, high-volume micro-EV producers like SAIC-GM-Wuling and Changan face a formidable precedent. While Wuling mastered low-cost domestic micro-mobility with unrefined architectures, BYD is demonstrating how to engineer a micro-EV that complies with rigorous international safety and homologation baselines. This divergence leaves rudimentary Chinese city cars confined to unregulated domestic lower-tier cities, while BYD builds a differentiated export portfolio tailored to strict global compliance mandates.
The Reality Check: Interrogating the Micro-Mobility Export Thesis
Despite the strategic appeal, corporate communications surrounding this export initiative omit critical engineering and economic bottlenecks. Industry observers must interrogate several foundational assumptions before accepting the premise that Japanese-spec kei-car EVs can achieve broad international scaling.
First, the structural physics of kei cars represent an ongoing safety liability in mixed-traffic international environments. In Japan, kei vehicles operate within an ecosystem governed by strict urban speed limits, sophisticated pedestrian infrastructure, and low truck presence. Transporting that same 3.4-meter, lightweight chassis onto the high-speed, poorly regulated arterial roads of South Asia or Latin America introduces severe passive safety risks. While BYD incorporates high-strength steel throughout the passenger cell and leverages the structural battery pack for side-impact protection, an 1,100 kg micro-vehicle remains vulnerable in collisions with multi-ton commercial transport vehicles. If international NCAP testing yields poor safety ratings, export viability in mature markets like the UK or Australia will vanish.
Second, the macroeconomic premise of testing vehicles in Sri Lanka warrants skepticism. Sri Lanka has experienced extreme foreign exchange volatility, balance-of-payments crises, and strict import restrictions designed to protect foreign currency reserves. While the island nation possesses an appetite for fuel-efficient vehicles due to elevated domestic petroleum prices, its electrical grid suffers from localized instability, generation deficits, and reliance on thermal generation. Pumping electric fleet additions into a fragile national grid without distributed solar infrastructure shifts the environmental and economic burden onto domestic utilities. Furthermore, consumer financing in such jurisdictions carries prohibitive interest rates, blunting the impact of low retail MSRPs.
Third, the profitability paradox inherent in micro-EVs cannot be bypassed indefinitely through vertical integration. With an anticipated retail price between $11,000 and $14,000, net profit margins per unit are exceptionally slim—likely in the low single digits (3% to 5%). To amortize the capital expenditures associated with RHD re-engineering, overseas Homologation certifications, and localized spare-parts warehousing, BYD requires massive production volume. If export sales in niche enclaves like Macau and Sri Lanka fail to transition into tens of thousands of annual units across major Tier-1 developing nations, the program risks becoming an operational distraction that drains engineering resources away from high-margin global platforms like the Song, Seal, and Yangwang.
Regulatory Adaptation and Geopolitical Realities
The international deployment of this micro-platform directly reflects the geopolitical friction surrounding Chinese industrial capacity. With the United States levying 100% tariffs under Section 301, the European Union implementing countervailing duties ranging up to 35.3% on top of baseline 10% auto tariffs, and domestic subsidies tightening, Chinese OEMs are encountering regulatory walls in primary Western export destinations. These tariff structures render standard Chinese compact and mid-size electric sedans substantially less competitive in transatlantic markets.
Consequently, targeting markets like Macau, Sri Lanka, and broader Southeast Asian or Latin American territories functions as a deliberate risk-mitigation strategy. Macau operates under a distinct legal and regulatory framework within the 'One Country, Two Systems' structure, maintaining right-hand-drive traffic regulations while offering complete exemption from Western trade sanctions. It serves as an optimal real-world stress test for right-hand-drive software localization, electronic tolling integration, and tight-radius autonomous parking systems.
In broader non-aligned markets, BYD avoids the national security investigations surrounding connected vehicle software that currently paralyze its entry into North America. By focusing on essential urban mobility platforms stripped of high-compute sensor suites (such as LiDAR or dual-Nvidia Orin architectures), the micro-EV does not trigger sovereign data-collection alarms. Instead, it relies on basic Level 1 and Level 2 driver assistance systems that comply with standard UNECE (United Nations Economic Commission for Europe) vehicle regulations, allowing BYD to secure market authorizations across developing signatories without encountering geopolitically driven technology bans.
Strategic Outlook and Executive Scenarios
The progression of BYD's micro-electric export drive will reveal whether hyper-compact urban architectures represent a genuine global product category or remain an isolated regional curiosity. Automotive strategists and investors should monitor three primary developmental trajectories over the coming 24 to 36 months.
Bull Case
BYD successfully validates the durability and thermal stability of its scaled LFP Blade architecture in the demanding urban environments of Macau and Sri Lanka, achieving high reliability ratings. Leveraging these operational data points, the OEM accelerates homologation for high-volume right-hand-drive markets across the UK, Australia, India, and ASEAN. By pricing the vehicle below £15,000 in the UK and under $15,000 equivalent across Southeast Asia, BYD establishes an unassailable monopoly over entry-level urban EV mobility, forcing Western and Japanese competitors to either cede the entry-level segment or source platform architectures directly from Chinese tier-1 suppliers under white-label partnerships.
Base Case
The micro-EV secures steady, modest adoption in densely populated city-states and tourism-heavy island economies where low daily mileage and restricted parking dictate vehicle footprints. However, broader expansion into high-speed suburban markets stalls due to consumer range anxiety and unfavorable highway crash test perceptions. The vehicle remains a niche urban fleet and delivery solution, generating modest operational profits while functioning primarily as an inexpensive brand ambassador that introduces first-time buyers to the BYD digital ecosystem.
Bear Case
Severe currency fluctuations and economic instability in frontier markets like Sri Lanka suppress sales volumes, preventing BYD from recovering its overseas distribution and homologation investments. Concurrently, safety watchdogs in mature export markets raise regulatory hurdles regarding side-impact survivability for narrow-track micro-vehicles, restricting the platform from entering lucrative Western RHD markets. The project is ultimately scaled back, confining the architecture to Japan's domestic market and Hong Kong/Macau, reinforcing the historical reality that kei-car dimensions are structurally incompatible with global consumer expectations.
Strategic Takeaways for Automotive Executives
- Vertical Integration Lowers the Platform Ceiling: BYD's deployment of in-house LFP Blade chemistry and internal power electronics demonstrates that micro-EVs can be engineered to meet basic international crash standards without blowing out entry-level pricing thresholds.
- Bypassing Western Tariff Walls: Faced with stringent EU countervailing duties and US exclusion, Chinese OEMs are aggressively pivoting toward unencumbered RHD frontier markets, establishing infrastructure footprints where legacy Western OEMs have no low-cost EV product pipeline.
- Safety Homologation Remains the Pivotal Bottleneck: The critical metric to track is not initial retail pricing, but how scaled kei architectures perform under standardized Euro NCAP or Global NCAP test protocols; structural performance under high-speed impact will dictate true global addressable market size.
- Legacy Moats Are Being Tested from the Bottom: Japanese automakers reliant on compact combustion vehicle sales across South and Southeast Asia must accelerate their own sub-$20,000 electrification timetables or risk losing foundational market share to vertically integrated Chinese micro-platforms.