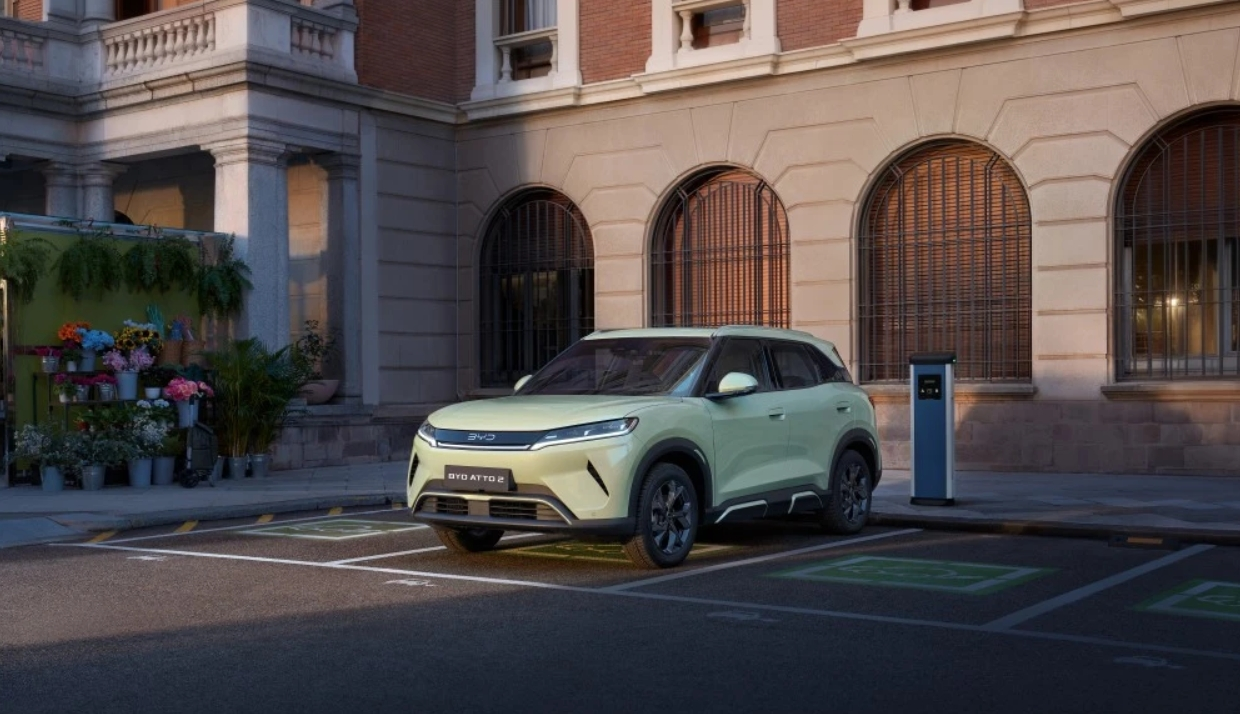
The global automotive landscape is poised to enter a new industrial era with the acceleration of the BYD European expansion strategy. For years, Western legacy automakers and institutional investors viewed Chinese electric vehicle (EV) manufacturers primarily as export-driven disrupters shipping completed units (CBU) from ports like Shenzhen and Shanghai. However, the appointment of veteran automotive executive Alfredo Altavilla—former Chief Operating Officer of Fiat Chrysler Automobiles (FCA)—as a special advisor for Europe signals a profound strategic shift. BYD is no longer merely seeking to sell vehicles in Europe; it is actively constructing a localized industrial ecosystem, planning up to three vehicle assembly plants and a dedicated battery cell facility on European soil.
To understand the gravity of this pivot, one must look at the historical context of Chinese automotive globalization. Early attempts by Chinese OEMs to penetrate European markets in the mid-2000s failed due to poor safety ratings and a lack of brand equity. Over the subsequent two decades, massive domestic market scaling, state-supported battery R&D, and absolute vertical integration allowed brands like BYD to leapfrog legacy combustion technologies. Now, facing saturated domestic markets and mounting geopolitical friction, BYD is deploying a highly sophisticated manufacturing footprint designed to integrate seamlessly into European value chains, ensuring long-term resilience against shifting trade policies.
Analyzing the Industrial Logic Behind the BYD European Expansion Strategy
The core of the BYD European expansion strategy lies in moving manufacturing close to the end consumer. Relying solely on pure ocean shipping is structurally unsustainable due to fluctuating roll-on/roll-off (RoRo) vessel charter rates, port congestion, and long transit times that delay cash conversion cycles. Localized production resolves these logistical bottlenecks while providing a powerful buffer against import tariffs. Under the current plans, BYD's manufacturing blueprint spans strategic nodes designed to capture distinct economic advantages across the continent.
The first major node is the passenger vehicle factory in Szeged, Hungary, representing an investment of billions of euros. Hungary has successfully positioned itself as a bridge between Western automotive standards and Eastern battery supply chains, offering attractive corporate tax structures and skilled labor. The second confirmed facility is the planned $1 billion production plant in Manisa, Turkey, which leverages Turkey's Customs Union agreement with the European Union to secure duty-free access to Western European markets. Additionally, discussions surrounding a third assembly plant and a massive FinDreams battery cell gigafactory highlight BYD's commitment to replicating its highly successful vertically integrated model directly inside Europe.
Technical Architecture of Localized Models: Platforms, Powertrains, and the Blade Battery
To succeed in the highly discerning European market, BYD's localized vehicles must deliver top-tier technical performance, safety, and efficiency. The cornerstone of BYD's current product offering is the e-Platform 3.0 Evo, an advanced 800V-capable architecture designed to support high-efficiency powertrains, ultra-fast charging, and advanced vehicle dynamics. This platform relies heavily on Cell-to-Body (CTB) structural integration, where the battery pack serves as a structural component of the vehicle chassis, increasing torsional stiffness and cabin space.
At the chemical level, BYD's proprietary Blade Battery—utilizing lithium iron phosphate (LFP) chemistry—offers distinctive thermal stability and safety advantages over traditional nickel-manganese-cobalt (NMC) cells. By using a long, thin, blade-like cell design arranged in a pack-free configuration, BYD achieves a volumetric integration efficiency of over 60%, largely mitigating the energy density penalties historically associated with LFP chemistry. Furthermore, BYD's highly integrated 9-in-1 electric powertrain combines the motor, inverter, transmission, and power distribution units, achieving a system efficiency of up to 92.5%.
| Metric / Parameter | BYD Sea Lion 7 (e-Platform 3.0 Evo) | Tesla Model Y (Long Range) | Volkswagen ID.4 (Pro) | Zeekr 001 (SEA Platform) |
|---|---|---|---|---|
| Architecture Voltage | 800V (SiC Inverter) | 400V (SiC Inverter) | 400V (IGBT Inverter) | 800V (SiC Inverter) |
| Cell Chemistry | LFP (Blade Battery) | NMC / LFP (Region-dependent) | NMC (High-Nickel) | NMC / LFP (Dual-option) |
| Battery Pack Capacity (kWh) | 82.5 / 91.3 | 75.0 / 81.0 | 77.0 / 82.0 | 95.0 / 100.0 |
| Max Charging C-Rate / Power | Up to 240 kW (2.5C) | Up to 250 kW (3.0C) | Up to 175 kW (1.8C) | Up to 540 kW (5C LFP) |
| Powertrain Integration | 9-in-1 Highly Integrated | 3-in-1 Modular | 3-in-1 Modular | Integrated Dual-Motor System |
Supply Chain Localization and BOM Economics under the BYD European Expansion Strategy
A critical question facing automotive analysts is whether BYD can maintain its structural cost advantages when manufacturing within high-cost European jurisdictions. In China, BYD benefits from extreme vertical integration, manufacturing everything from traction motors and thermal management systems to automotive semiconductors (via BYD Semiconductor) and battery cells (via FinDreams). This extensive in-house production allows BYD to capture margins at every stage of the value chain, resulting in a Bill of Materials (BOM) cost that is estimated to be 20% to 30% lower than that of legacy European automakers.
When transitioning to a localized manufacturing footprint in Europe, BYD will face higher labor rates, increased energy costs, and strict environmental regulations. However, BYD's supply chain localization strategy is designed to mitigate these localized cost premiums. By establishing its first vehicle assembly plants in Hungary and Turkey—where manufacturing wages are competitive relative to Western Europe—BYD keeps direct labor assembly costs low. Furthermore, by constructing localized battery cell manufacturing, BYD avoids the massive transport duties and safety risks associated with shipping heavy battery packs across oceans. Over time, as Tier-1 suppliers like Bosch, Continental, and local steel makers integrate into BYD's localized supplier network, the economic benefits of local scale will offset the initial capital expenditure premium, securing a sustainable structural cost edge over legacy OEMs.
The Impact of BYD's Localized Sourcing on Western Legacy OEMs
The physical arrival of BYD factories in Europe represents an unprecedented competitive challenge for European legacy auto giants such as Volkswagen Group, Stellantis, Renault, and Mercedes-Benz. Historically, Western legacy OEMs relied on their domestic manufacturing dominance, localized dealer networks, and strong brand heritage to maintain market share. However, as localized BYD vehicles begin rolling off assembly lines in Hungary and Turkey, the historical barriers protecting European OEMs will shift rapidly.
This industrialization will exert intense margin pressure on European automakers, particularly in the highly competitive B- and C-segment EV categories. Vehicles like the BYD Dolphin and Atto 3, followed closely by localized versions of the Sea Lion 7, will directly target the heart of the European mass market. Unlike imported Chinese EVs, which carry additional shipping overhead and potential trade duties, localized BYD vehicles will benefit from streamlined regional supply chains. This allows BYD to offer cutting-edge technology—such as advanced heat pumps, 800V architectures, and integrated ADAS suites—at price points that legacy OEMs will struggle to match without sacrificing their own operating margins. This competitive pressure will likely accelerate cross-border collaborations, supply chain modernization, and deeper industry-wide consolidation across the European continent.
Geopolitical Dynamics and Tariff Compliance Frameworks
The geopolitical reality of the modern global automotive industry dictates that trade compliance is just as critical as engineering excellence. The European Commission's implementation of individual countervailing duties on Chinese-manufactured EVs has made pure export strategies economically challenging. In this regulatory environment, the BYD European expansion strategy is a textbook example of proactive trade adaptability and compliant regional planning.
By investing heavily in local manufacturing hubs within Europe, BYD aligns its operations with localized value creation, job creation, and industrial tax contributions. The plant in Hungary operates directly within the EU single market, ensuring complete compliance with regional origin rules and eliminating any exposure to import tariffs on finished vehicles. Similarly, the plant in Turkey leverages the long-standing EU-Turkey Customs Union, allowing for seamless, duty-free trade of industrial goods once local-content thresholds are satisfied. This constructive, compliant approach to localization demonstrates how global EV manufacturers can adapt to regional regulatory requirements while fostering positive local economic development and supporting European decarbonization targets.
A 3-5 Year Scenario Analysis of the BYD European Expansion Strategy
The medium-term success of BYD's localized European industrial footprint depends on multiple variables, from consumer adoption rates to macroeconomic stability. Below, we map out three potential strategic scenarios over the next three to five years.
Bull Case Scenario
In this high-growth scenario, BYD's Hungarian and Turkish assembly plants reach full nameplate capacity ahead of schedule, producing over 350,000 vehicles annually. Localized FinDreams battery gigafactories seamlessly supply cells, bringing localized BOM costs in line with original projections. European fleet operators and retail buyers rapidly adopt BYD's localized models, drawn to their advanced LFP safety profile and competitive pricing. BYD successfully establishes a robust brand presence, securing a stable 5% to 8% share of the European passenger EV market, while remaining fully compliant with all regional trade and environmental frameworks.
Base Case Scenario
Under the base case, BYD experiences steady, incremental growth in Europe. Plant construction and tool-up phases proceed in alignment with standard timelines, with localized production scaling gradually over 24 to 36 months. Initial localized vehicles face mild headwinds due to highly competitive marketing from defensive legacy OEMs and localized pricing adjustments. However, BYD's robust technological advantages and reliable localized supply chains ensure steady market share gains, allowing the brand to capture a solid 3% to 5% share of the European EV market by 2030, supported by solid dealer networks and strong customer satisfaction ratings.
Bear Case Scenario
In the low-growth scenario, macroeconomic headwinds, persistent inflation, and rising energy costs across Europe dampen overall EV consumer demand. BYD faces localized supply chain bottlenecks, labor integration challenges, and delays in bringing its localized battery cell manufacturing online. Furthermore, aggressive pricing actions from highly localized competitors, combined with lingering consumer brand unfamiliarity, slow the ramp-up of the Hungarian and Turkish plants, keeping capacity utilization low and delaying the timeline to operational profitability.
Strategic Implications for Global Executives and Institutional Investors
For executive decision-makers and institutional investors, the localized BYD European expansion strategy offers critical strategic takeaways that should guide capital allocation and supply chain planning:
- Rethink the Global Supply Chain Paradigm: The era of centralized, low-cost country export manufacturing is shifting toward regionalized, localized industrial clusters. Global automotive suppliers must establish co-located facilities near emerging manufacturing hubs in Eastern Europe and Turkey to secure long-term supply contracts.
- Evaluate LFP and CTB Technologies: BYD's deployment of localized LFP chemistry and Cell-to-Body structural integration will accelerate European market acceptance of cobalt-free chemistries. Investors should monitor how rapidly European tier-1 battery suppliers can scale local LFP production to meet this shifting demand.
- Prepare for Sustained Competitive Pressures: Western legacy OEMs must accelerate their own platform development and software integration to remain competitive. Strategic partnerships, joint ventures, and technology licensing with global leaders will become increasingly vital to maintain operating margins and scale localized EV architectures efficiently.
- Focus on Regional Value Creation: Successful globalization now requires building deep, compliant roots in host countries. Companies that prioritize local job creation, community development, and sustainable sourcing will navigate complex trade environments far more successfully than those relying purely on cross-border export models.
