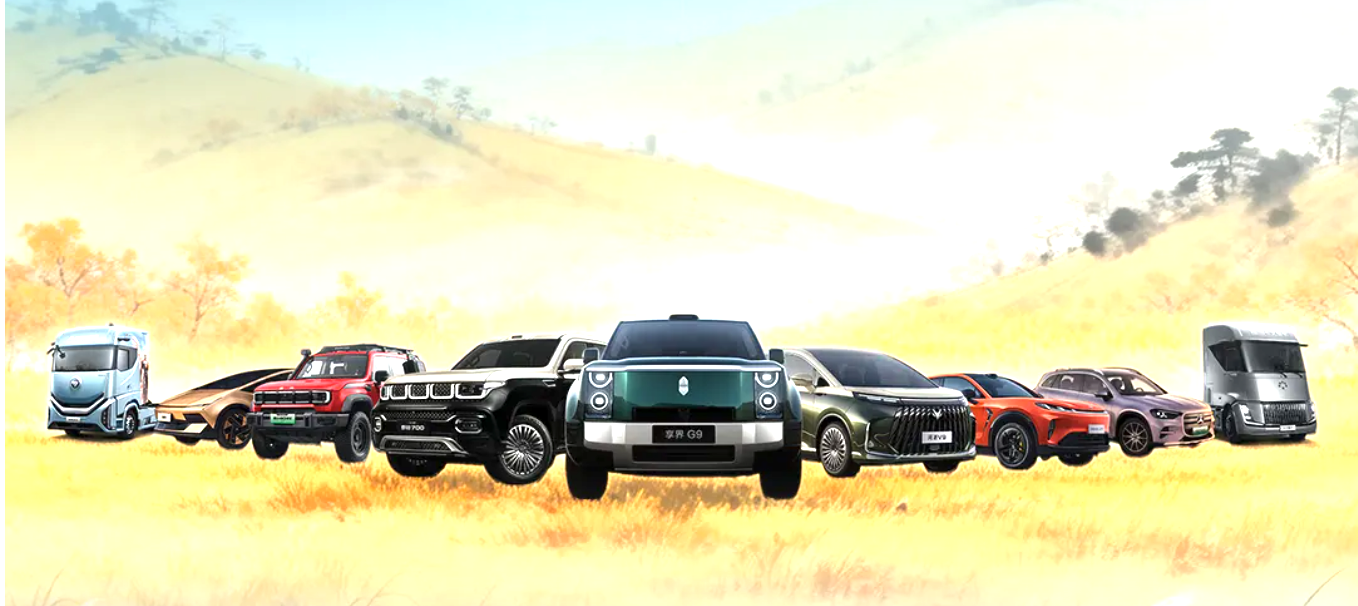
When state-owned automotive giant Beijing Automotive Industry Holding Co. (BAIC Group) published its delivery figures for the first three quarters of the year, reporting group-wide sales exceeding 1.167 million units and nine consecutive months of double-digit export expansion, domestic financial pages celebrated another triumph for China's manufacturing machine. Yet, institutional analysts and Western tier-1 executives parsing the data through a skeptical lens see a far more complex, precarious industrial tightrope. Behind the headline delivery figures lies an aggressive push to offload capacity into emerging markets while structural margins in mainland China collapse under unrelenting domestic price wars.
Historically, BAIC has occupied an ambivalent position among China's state-owned automotive enterprises (SOEs). Unlike private nimble disruptors such as BYD or Geely, BAIC's balance sheet has historically functioned as a financial conduit for profitable joint ventures—chiefly Beijing Benz and, formerly to a greater extent, Beijing Hyundai. For years, the cash distributions from manufacturing Mercedes-Benz C-Class and E-Class sedans subsidised the slower, state-directed electrification of BAIC's proprietary marques. Today, with foreign joint-venture volumes softening across the Chinese mainland and Western markets erecting formidable trade ramparts, BAIC's pivot toward self-developed passenger vehicle exports and Huawei-assisted smart EV architectures represents an existential repositioning rather than a mere organic expansion.
Powertrain Realities: Dissecting the Hybrid and Pure Electric Architecture
To evaluate whether BAIC's operational volume translates into a sustainable technological moat, one must dissect the engineering architectures underpinning its current portfolio. The group's lineup spans three divergent vehicle platforms: rugged, hybrid off-roaders under the Beijing Off-Road (BJ) badge, commercial light vehicles under Beiqi Foton, and the high-voltage, software-centric battery electric platforms developed for its Arcfox marque.
Consider the engineering divide between BAIC's export volume drivers and its domestic technological showcases. In overseas markets across Central Asia, the Middle East, and Latin America, the volume backbone remains internal combustion engines (ICE) and entry-level plug-in hybrid (PHEV) platforms like the BJ30 and BJ40. The BJ40 relies on a conventional 2.0-liter turbocharged four-cylinder paired with an 8-speed automatic transmission or a dual-motor P2/P4 hybrid configuration. While rugged and mechanical, these platforms offer thermal efficiencies hovering around 38.5% to 40.5%—respectable, but technologically trailing the 44% to 46% thermal efficiency records achieved by Geely's NordThor and BYD's DM 5.0 systems. These legacy architectures are inexpensive to manufacture, resilient against lower-grade fuels, and unencumbered by Western silicon sanctions, making them ideal for unregulated emerging jurisdictions, but fundamentally disconnected from the premium electrification narrative presented to international capital markets.
Conversely, BAIC's technological spearhead, the Arcfox marque—co-engineered with Canadian-Austrian tier-1 contract manufacturer Magna International at their Zhenjiang joint-venture facility—employs dedicated high-voltage battery-electric architecture. The Arcfox αS5 and αT5 ride on an 800-volt Silicon Carbide (SiC) power electronic platform capable of peak charging rates approaching 2.6C to 3.0C when connected to compatible high-power DC infrastructure. The vehicles integrate ternary lithium (NCM) and lithium iron phosphate (LFP) chemistry options, with cell-to-pack (CTP) structural integration achieving pack-level volumetric efficiencies of roughly 65%.
| Metric / Specification | BAIC Arcfox αS5 | BYD Seal (EV) | GWM Tank 500 Hi4-T | Chery Jaecoo J7 (PHEV) |
|---|---|---|---|---|
| Architecture Voltage | 800V SiC Platform | 400V / 800V e-Platform 3.0 | 370V P2 Hybrid Platform | 400V Dedicated Hybrid (DHT) |
| Battery Chemistry & Capacity | 79.2 kWh Ternary NCM (CATL) | 82.5 kWh LFP Blade Battery | 37.1 kWh NCM Ternary (SVOLT) | 18.3 kWh LFP (Guoxuan) |
| Peak DC Fast-Charge Rate | 250 kW (approx. 2.8C) | 150 kW (approx. 1.8C) | 50 kW (approx. 1.3C) | 40 kW (approx. 2.1C) |
| Autonomous Compute Hardware | Huawei MDC 610 (200 TOPS) | Orin-X / Proprietary DiPilot | Mobileye EyeQ4 / Texas Inst. | Horizon Robotics Journey 3 |
| Thermal Efficiency (PHEV/ICE) | N/A (Pure BEV) | N/A (Pure BEV) | 38.0% (2.0T Millercycle) | 44.5% (1.5TGDI DHE) |
| Base Export ASP (Estimated FOB) | $28,500 USD | $24,000 USD | $36,000 USD | $18,500 USD |
As illustrated, while Arcfox demonstrates competitive 800V electrical specifications that match or exceed mainstream BYD sedans on paper, its commercial export footprint remains negligible compared to its ICE and commercial vehicle counterparts. The high-voltage SiC architectures that impress automotive engineers account for only a modest single-digit fraction of the 1.167 million units delivered year-to-date, exposing the stark divergence between corporate marketing narratives and actual export volume composition.
Supply Chain Dynamics: Huawei Alliance and Tier-1 Cost Structures
A granular examination of BAIC's supply chain reveals both significant technological leverage and acute margin vulnerability. Unlike BYD, which has systematically vertically integrated battery cell manufacturing, power semiconductor fabrication (SiC and IGBT modules), and electric drive production, BAIC remains fundamentally reliant on a merchant supply model. This exposes its proprietary vehicles to higher Bill of Materials (BOM) costs.
For high-voltage energy storage, BAIC sources almost exclusively from Contemporary Amperex Technology Co. Limited (CATL). While CATL's Shenxing 4C LFP and Qilin NCM cells provide class-leading energy densities and thermal stability, BAIC lacks the procurement scale of Geely or the internal manufacturing margins of BYD. Industry teardowns estimate that BAIC pays approximately $78 to $84 per kilowatt-hour at the pack level for standard LFP configurations, compared to BYD's estimated internal manufacturing cost of sub-$65 per kWh for its Blade battery system. In an aggressive price-deflationary environment, this $15 to $20 per kWh structural cost gap strips hundreds of dollars of operating margin out of every entry-level passenger vehicle produced.
In intelligent driving and smart cockpit integration, BAIC has surrendered significant proprietary control to Huawei Technologies through both the HI (Huawei Inside) model and the newer Smart Selection (HIMA) alliance via the Stelato (Xiangjie) executive sedan brand. The Stelato S9 incorporates Huawei's 192-channel LiDAR, the MDC 810 computing platform delivering up to 400 TOPS of dense inference performance, and the HarmonyOS digital cockpit. While this technological partnership grants BAIC immediate access to one of China's most sophisticated Mapless Navigation on Autopilot (NOA) suites, it alters the economic equation. Huawei's comprehensive hardware-software stack extracts an estimated licensing and tier-1 procurement fee of 25,000 to 35,000 RMB ($3,500 to $4,900 USD) per vehicle, severely compressing BAIC's gross margin on each flagship model sold.
Beneath the premium electronics tier, BAIC relies on established global suppliers for chassis dynamic control and power delivery. German tier-1 supplier Bosch supplies the integrated IPB (Integrated Power Brake) brake-by-wire modules, while United Automotive Electronic Systems (UAES)—a joint venture between Bosch and SAIC—provides high-voltage silicon carbide motor inverters. This reliance on premium, non-captive components guarantees high vehicle assembly quality—buttressed by Magna's Zhenjiang manufacturing oversight—but structurally inflates the cost base, rendering it extraordinarily difficult for BAIC to wage sustained price wars without eroding operational cash reserves.
Competitive Impact Assessment: The Margin Squeeze Between Domestic Giants and Global Challengers
The aggressive volume expansion reported by BAIC reverberates unevenly across the competitive automotive landscape. Domestically, the group finds itself squeezed in a brutal vice between private cost leaders and specialized EV pure-plays. In the entry-to-mid market (100,000 to 200,000 RMB), BYD's vertical scale and Geely's multi-brand modularity (Galaxy, Lynk & Co) systematically cannibalize BAIC's conventional passenger car volumes. In the premium software-defined vehicle segment (300,000+ RMB), despite the launch of the Stelato S9 with Huawei, BAIC must contend with Li Auto, Nio, and Tesla, all of whom possess stronger consumer software brand equity.
Globally, the dynamic inverts. BAIC's export offensive is not targeting Frankfurt, Los Angeles, or London, where Western OEMs are preparing defensive regulatory moats. Instead, BAIC is executing a flanking maneuver into non-aligned automotive markets: Latin America (Chile, Peru, Mexico), the Middle East (Saudi Arabia, UAE), Southeast Asia, and selected African economies. In these territories, BAIC's aggressive pricing on rugged internal-combustion off-roaders and affordable light-commercial Foton trucks directly pressures traditional Japanese and European incumbents:
- Toyota and Isuzu: In emerging markets where the Hilux and D-Max have historically enjoyed unchallenged pricing power, Foton's commercial trucks and pickups offer 85% of the mechanical capability at a 25% to 35% discount in upfront capital expenditure.
- Stellantis and Renault: In regions like North Africa and South America, BAIC's compact crossovers (such as the X55) challenge entry-level European crossovers by bundling Level 2 ADAS features, panoramic digital cockpits, and dual-clutch powertrains at price points that traditional European platforms struggle to match profitably.
- Chinese Competitors Abroad: BAIC does not operate in a vacuum overseas. It faces ferocious internecine competition from Chery Automobile—the perennial leader among Chinese vehicle exporters—and Great Wall Motor (GWM). Chery's Tiggo and Jaecoo lineups and GWM's Haval and Tank series compete for identical demographic segments across Latin America and the Middle East, triggering export-market margin degradation reminiscent of the domestic Chinese price war.
The Reality Check: Interrogating the 1.16 Million Headline Deliveries
A rigorous analytical cross-check of corporate disclosures against operational reality reveals critical fault lines beneath BAIC's celebrated sales metrics. Institutional investors must interrogate the quality, profitability, and durability of these 1.167 million units.
First, the aggregate volume continues to be heavily supported by commercial utility and fleet channels rather than high-margin private retail consumption. Beiqi Foton's commercial vans, light-duty cargo trucks, and agricultural-adjacent vehicles comprise a massive component of group-wide shipments. These commercial vehicles operate on paper-thin operating margins—frequently between 1.5% and 3.5% net—and are vulnerable to cyclical downturns in logistics and infrastructure spending. Celebrating over a million deliveries without segregating retail passenger electrification from commercial fleet churn presents an incomplete picture of brand equity.
Second, the narrative of "overseas double-digit growth" requires geographic deconstruction. Much of this growth stems from filling vacuum markets abandoned by Western OEMs following the 2022 geopolitical fracture, notably the Russian Federation, alongside opportunistically targeting non-tariffed regions. In these territories, the vehicles sold are predominantly legacy internal combustion and entry-level dual-fuel engines. Selling mechanical gasoline crossovers into developing markets provides immediate inventory liquidation and keeps factory utilization rates above critical breakeven thresholds (typically 75% to 80%), but it does virtually nothing to advance BAIC's global transition toward battery-electric software-defined mobility.
Third, the flagship Arcfox brand remains an ongoing drag on corporate operating cash flow. Despite substantial capital allocation, high-profile design appointments, and the Magna manufacturing imprimatur, Arcfox's domestic monthly registrations have historically languished in the low-thousands—frequently failing to breach 5,000 units per month until recent aggressive retail price cuts were implemented. To stimulate volume, BAIC resorted to offering the Arcfox αT5 at sub-130,000 RMB ($18,200 USD) price brackets—a pricing posture that automotive supply chain analysts estimate barely covers the raw physical BOM and logistics costs, leaving R&D amortization completely unaddressed.
Finally, claims regarding advanced autonomous capabilities—specifically the Level 3 readiness touted for vehicles integrated with Huawei's intelligent driving stacks—remain strictly confined to geofenced, high-definition-mapped pilot corridors in Tier-1 Chinese municipalities. In international export jurisdictions, the high-compute sensor suites and advanced algorithms are completely deactivated or downgraded to standard Level 2 highway cruising due to the absence of overseas HD mapping infrastructure, localized data-sovereignty compliance, and foreign regulatory homologation. Western and emerging market consumers purchasing these vehicles overseas are paying for idle processing silicon that cannot execute its primary design functions.
The Regulatory and Geopolitical Landscape: Tariff Fortresses and Compliant Localization
As BAIC accelerates its international push, it encounters an increasingly hostile global trade apparatus designed to neutralize state-supported automotive supply chains. The geopolitical environment necessitates a total transformation of how Chinese OEMs approach global logistics.
In North America, the United States' Section 301 tariffs, combined with the Inflation Reduction Act's Foreign Entity of Concern (FEOC) restrictions, effectively close the market to Chinese-assembled connected vehicles and battery packs containing Chinese-sourced active materials. Even BAIC's light commercial ambitions via Foton face regulatory containment. In the European Union, the European Commission's countervailing duties on imported battery-electric vehicles impose supplementary tariffs ranging from 17% to over 35% on top of existing 10% base duties. While BAIC's current European footprint is minimal compared to SAIC (MG) or Geely, these tariffs eliminate any immediate prospect of profitably exporting Arcfox electric sedans directly from its Zhenjiang manufacturing base into Rotterdam or Antwerp.
Consequently, BAIC's foreign operations are forced into strategic localization models. Rather than relying on direct Completely Built-Up (CBU) oceanic shipping, BAIC is expanding Completely Knocked Down (CKD) and Semi-Knocked Down (SKD) assembly facilities in compliant territories. Key initiatives include:
- Southeast Asian Hubs: Utilizing regional free-trade frameworks under RCEP (Regional Comprehensive Economic Partnership) to establish knock-down assembly hubs in countries like Malaysia and Thailand, progressively scaling local value-add to bypass external trade frictions.
- Middle Eastern & African Infrastructure: Leveraging long-standing CKD operations in South Africa and forming joint venture assembly pacts in Egypt and the Gulf Cooperation Council (GCC) region. These facilities allow BAIC to assemble commercial trucks and rugged off-road vehicles locally, reducing inbound duty exposures from 20-30% down to low single digits while satisfying regional content mandates.
- Supply Chain Compliance Structuring: Carefully compartmentalizing intellectual property and telematics servers to avoid national security scrutiny. In emerging markets with emerging data-residency laws, BAIC must ensure that vehicle telematic data is stored locally rather than routed through mainland server architectures.
Strategic Scenarios and Institutional Investor Implications
The convergence of slowing domestic joint-venture cash flows, aggressive export initiatives, and high-capital software partnerships places BAIC Group at a strategic pivot point. Over the next 24 to 36 months, institutional investors and industry observers should monitor three distinct trajectories:
Bull Case
In this scenario, BAIC successfully stabilizes its domestic market share via the Huawei HIMA-backed Stelato alliance, capturing high-margin corporate executive sales that offset declining Beijing Benz margins. Overseas, its CKD assembly pivots in the Middle East, Southeast Asia, and South America scale smoothly, driving export volumes past 250,000 units annually with positive operating cash flow. The group effectively leverages its Foton commercial footprint as a trojan horse to distribute electrified light-duty vans, establishing brand credibility before transitioning those distribution channels toward mass-market passenger EVs.
Base Case
The group sustains headline delivery numbers above 1.1 million to 1.2 million units annually, but operating margins remain constrained between 1.5% and 2.5%. Overseas double-digit export momentum moderates as rival Chinese OEMs (Chery, Changan, GWM) engage in localized price-slashing across Latin America and the Middle East. Arcfox remains a low-volume domestic niche brand that struggles for export recognition, while Beijing Benz continues to supply the lion's share of group net profit, leaving BAIC vulnerable to any acceleration in China's luxury EV transition away from legacy German marques.
Bear Case
Rising geopolitical friction and expanded secondary trade penalties disrupt BAIC's lucrative emerging-market channels, while domestic price wars force deeper discounts across its proprietary Beijing Off-Road and Arcfox lineups. Operating cash flow turns negative as Mercedes-Benz JV profits contract faster than self-developed marques can achieve breakeven scale. High procurement outlays for external battery cells and Huawei computing platforms create persistent structural deficits, forcing municipal state shareholders to intervene with equity injections or orchestrate an industrial consolidation with another regional state-owned automotive conglomerate.
For supply chain directors, institutional equity analysts, and global automotive strategists, the critical takeaways from BAIC Group's current trajectory are unequivocal:
- Disaggregate Headline Growth: Never equate top-line group delivery volumes with electric vehicle transition velocity; assess proprietary passenger NEVs independently from commercial fleet and ICE joint-venture output.
- Scrutinize Merchant Bill-of-Materials: Un-integrated OEMs that rely on merchant tier-1 suppliers for both battery chemistry (CATL) and intelligent computing (Huawei) face structural margin ceilings during prolonged price deflation.
- Recognize the Geographic Split: China's state-owned automotive export growth is currently decoupling into a two-tier strategy: advanced high-voltage software showcases designed for domestic urban centers, contrasted against mechanical, legacy-propulsion workhorses shipped to emerging markets.
- Prepare for Global Flanking: Western legacy OEMs must recognize that the competitive threat from Chinese state-owned champions is concentrating in their historically profitable peripheral markets—Latin America, Southeast Asia, and the Middle East—where price sensitivity eclipses brand heritage.